Financial Statement Preparation Preparation of Balance Sheet, Profit & Loss Account, and Cash Flow Statements
Financial Statement Preparation is the process of preparing structured financial reports such as the Balance Sheet, Profit & Loss Account, and cash flow statements based on the business’s books of account and financial records. These statements are essential for compliance, financial reporting, audit support, and loan or funding requirements.
What is Financial Statement Preparation?
Financial Statement Preparation is the process of converting accounting records into structured financial reports that present the financial position and performance of a business. The key statements typically include the Balance Sheet, the Profit & Loss Account, and the Cash Flow Statement where applicable.
These statements are generally prepared from the books of account, ledger balances, bank statements, reconciliations, and year-end adjustments. The format and presentation are guided by the applicable accounting and legal framework, depending on the type of entity and reporting requirement.
Properly prepared financial statements are important for annual compliance, internal reporting, loans, investor review, tax filings, and audit support. Accuracy is critical because errors in financial statements can affect both compliance outcomes and business decision-making.
Benefits of Financial Statement Preparation
Accurate financial statements support regulatory, business, and financing requirements.
-
Compliance It helps businesses meet annual financial reporting and statutory compliance requirements under the applicable framework.
-
Financial Reporting It provides structured reports that reflect the financial position, profitability, and cash movement of the business.
-
Loan Support It supports bank loan applications, credit review, and funding discussions by presenting formal financial statements.
Documents Required
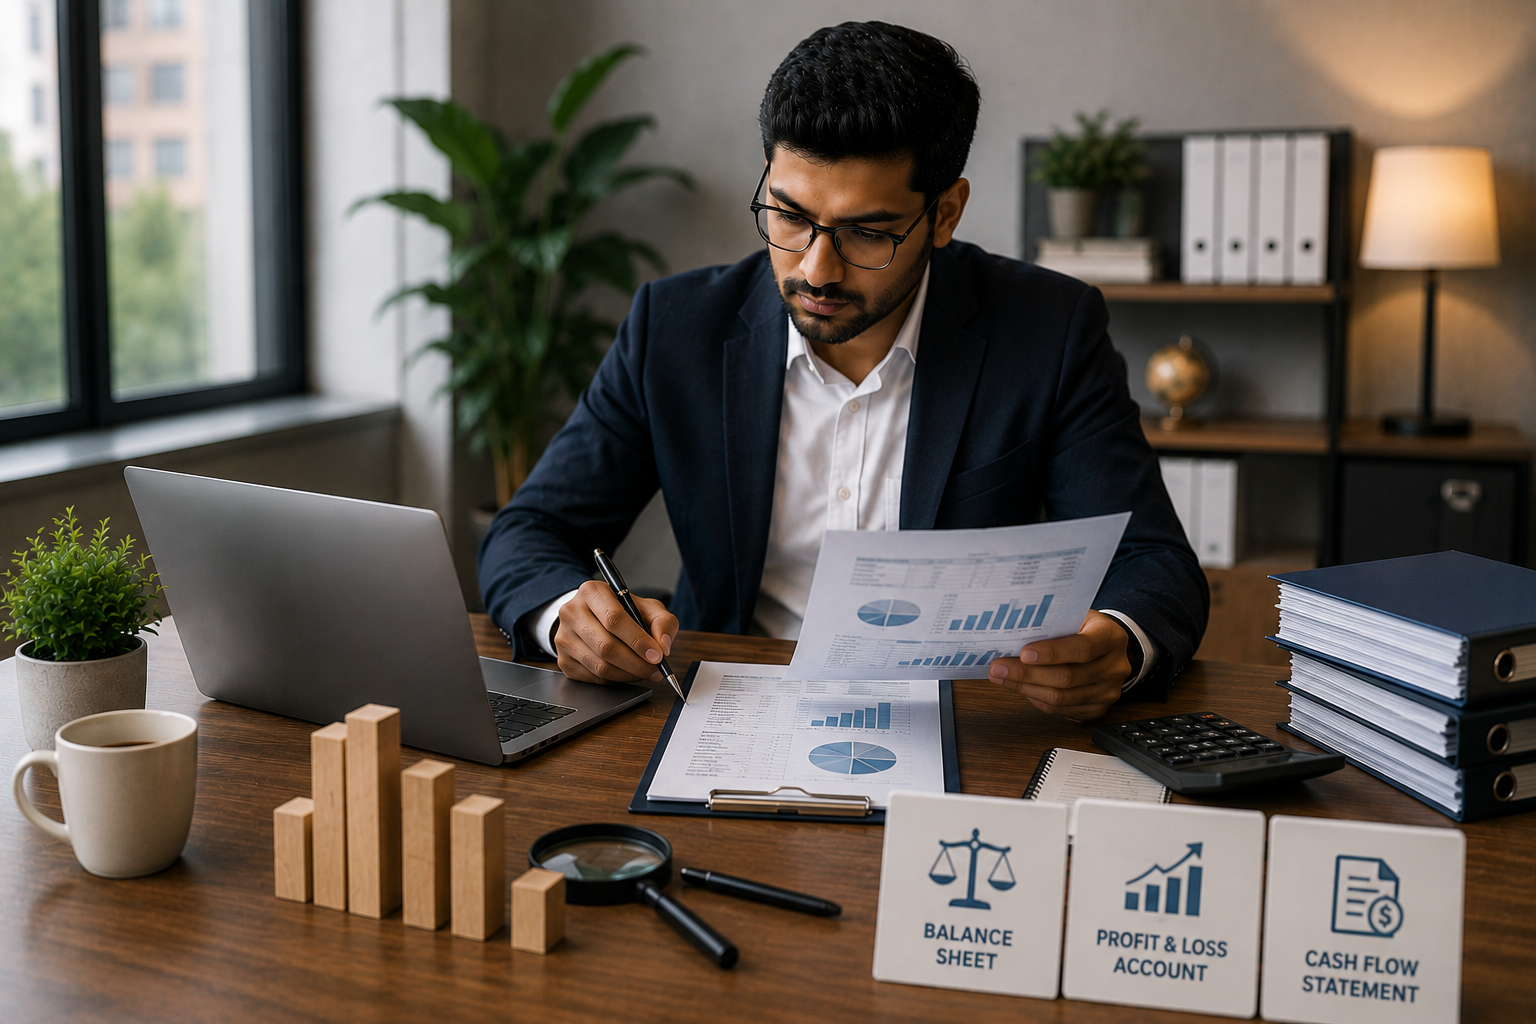
Financial statements are generally prepared from the accounting records and supporting financial documents of the business.
Books of Accounts
The books of accounts, ledgers, trial balance, and supporting schedules form the core base for preparing the financial statements.
Bank Statements
Bank statements are required for reconciliation, cash and bank balance confirmation, and accuracy of financial reporting.
Process & Timeline
Financial statement preparation is generally completed within about 5–10 days in standard cases, depending on record completeness, reconciliations, and adjustments.
Review Books of Accounts
Review the books, ledgers, and trial balance to ensure that accounting records are complete and properly classified.
Reconcile Bank & Key Balances
Match bank statements and major balances with the books to identify missing entries, mismatches, or required adjustments.
Prepare Statements
Prepare the Balance Sheet, Profit & Loss Account, and cash flow statement where applicable, along with supporting schedules.
Final Review & Reporting
Review the statements for accuracy, compliance, and presentation before using them for filing, audit, reporting, or loan purposes.
Get Started — Apply Now
Fill in the form below and one of our accounting professionals will help you prepare accurate and compliance-ready financial statements.
Frequently Asked Questions
Yes, financial statement preparation is generally mandatory under the applicable annual financial reporting framework.
They are commonly prepared by an accountant or Chartered Accountant depending on the entity and reporting requirement.
Audit is required in some cases depending on the type of entity, applicable law, and financial thresholds.
They are typically prepared annually, though interim statements may also be prepared for management or lender purposes.
Yes, financial statements are commonly used for bank loans, credit assessment, and funding support.
Yes, accuracy is critical because the statements are relied upon for compliance, audit, tax, and financial decisions.
The format is generally guided by the applicable legal and accounting framework and may be fixed or standardised for many entities.
Yes, digital accounting records and electronic preparation of statements are commonly used and accepted in practice subject to applicable requirements.
The work usually takes a few days in standard cases where books and reconciliations are ready.
The relevant authority depends on the use case, but MCA and income-tax reporting frameworks are commonly involved.